Geico Auto Repair vs Dealership Body Shops
I’ve filed three Geico auto repair insurance claims in five years, and one hard truth keeps repeating: the policy language matters less than the shop that touches your car. Geico pays what it deems reasonable, never what a dealership dreams up. Before choosing a repair route, a complete auto repair insurance guide is worth two minutes, because claims, deductibles, and network rules rarely change.
Table of Content
What Does Geico Auto Repair Insurance Cover?
Mechanical Breakdown Insurance Explained
Mechanical Breakdown Insurance is Geico’s flagship add-on for newer cars, and it behaves more like a repair claim than a traditional warranty. Quotes typically land between roughly thirty and ninety dollars every six months, and a single $250 deductible covers every unrelated repair performed during one visit. That per-visit structure is the detail most owners miss when they compare it against a manufacturer’s extended plan.
What the Auto Repair Express Network Includes
Geico routes smaller jobs to Auto Repair Express locations, which handle dents, bumpers, and glass on tight schedules. A network shop agrees to Geico’s labor rates and inspection standards, and in exchange the insurer backs the finished work for as long as you own the vehicle. That written guarantee is the real product, far more than the discounted hourly rate printed on your invoice.
Deductibles, Limits, and OEM Parts
Part choice drives most repair arguments. Geico can specify recycled or aftermarket components on older vehicles when no safety system is affected, though several states require your written consent for non-OEM crash parts. If you drive something past 100,000 miles, repair coverage for used cars rarely mirrors what gets sold on a new-car lot, and the gap only surfaces two winters later.
| Option | What it pays for | Typical deductible | Ideal for |
|---|---|---|---|
| Mechanical Breakdown Insurance | Mechanical failures on newer cars, with all unrelated items covered per visit | $250 per visit | Owners keeping a new car five years or longer |
| Collision and comprehensive | Accident damage and non-collision events | $250 to $1,000 | Anyone financing or leasing |
| Third-party extended warranty | Listed components after the factory term ends | $0 to $200 | High-mileage used cars, terms vary widely |
| Manufacturer warranty | Defects in materials or workmanship | $0 | The first three to five years |
Geico Network Shops vs Dealership Body Work
Dealer Body Shops and Hidden Sublets
Plenty of drivers assume the dealership delivers the best body repair. In reality, service departments focus on mechanical work, and many franchise dealers quietly sublet collision jobs to the same third-party shops you could have called yourself. An appraiser with a decade of estimating experience will tell you a bumper repair from a dealer and one from a competent independent shop look identical a year later.
Independent Shops and Warranty Gaps
Choosing an independent shop outside the network is perfectly legal, but you absorb the risk. Geico still pays a reasonable repair amount; what it will not do is stand behind workmanship it never inspected. If that shop takes six weeks and your rental coverage runs dry on day twenty, the difference comes out of your pocket, not your insurer’s.
Cost Differences That Actually Matter
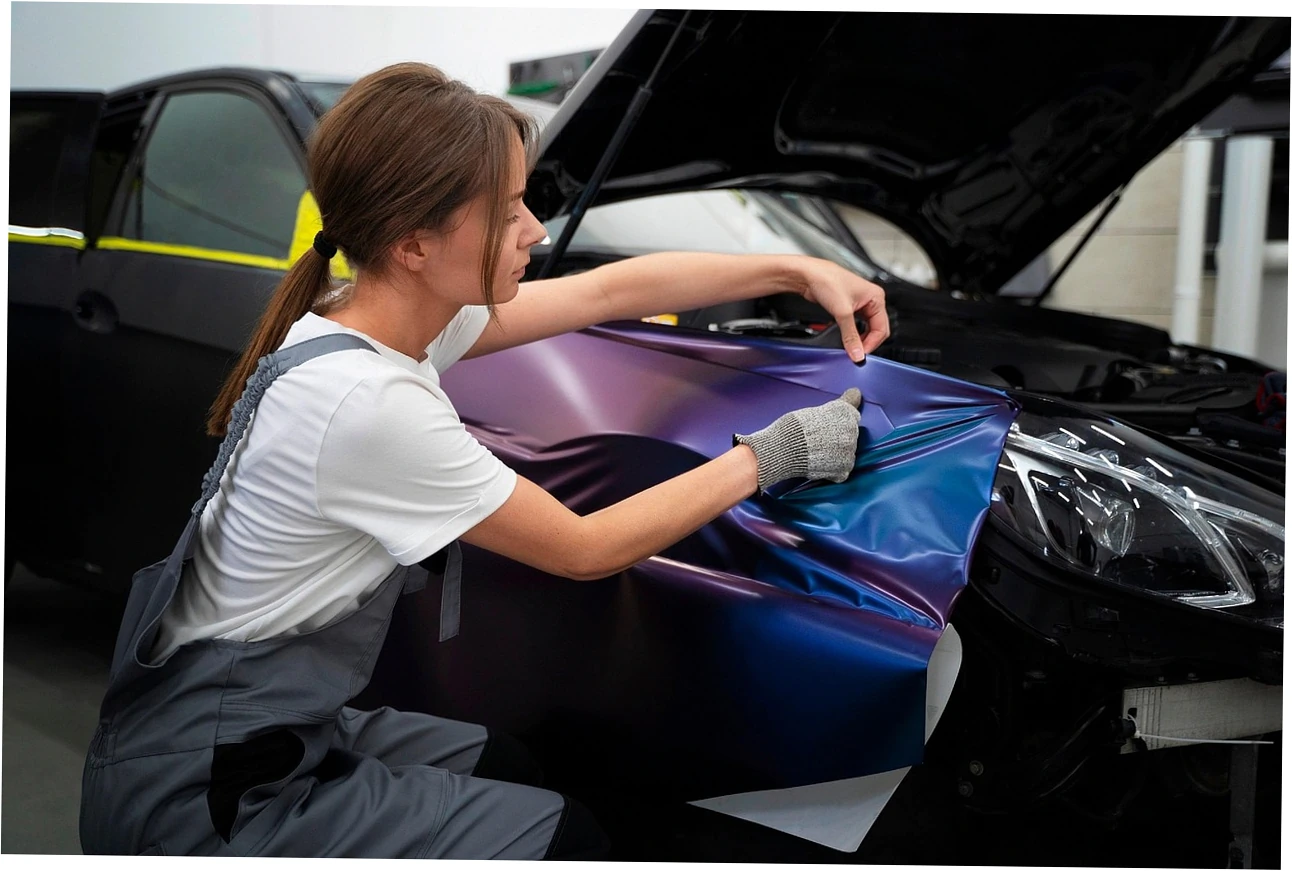
Network labor rates usually sit fifteen to thirty percent below dealership rates, and Geico writes its estimate around that figure rather than around your expectations. Shoppers comparing best auto repair insurance companies look at shop access and parts policy instead of glossy advertising. Certifications matter too: I-CAR Gold Class and ASE credentials signal technicians trained on modern repair procedures, not just quick dent pulling.
| Issue | Geico’s stated position | Owners’ reported experience |
|---|---|---|
| Repair warranty | Network work is backed for as long as you own the car | Most confirm smooth repairs; a few had to push for reassignment after poor work |
| Parts used | Repairs meet industry standards and state law | A minority report cheap materials or rushed craftsmanship on smaller jobs |
| Shop choice | Any shop is allowed, warranty applies in-network | Drivers confirm covering rental overruns themselves off-network |
| Claim handling | Adjusters estimate the reasonable cost of repair | Some mechanics decline the authorization process entirely |
| MBI billing | One deductible per visit across unrelated repairs | Widely confirmed, and owners call it unusually generous |
Is Geico Mechanical Breakdown Insurance Worth Buying?
Real Costs for Real Drivers
Cost is where MBI earns its reputation. One owner reported paying roughly twenty-two dollars per six-month term and later collecting more than five thousand dollars in repairs, including leaking electronic dampers and an HID bulb that the manufacturer’s warranty wrote off as wear and tear. Individual quotes swing widely by model, mileage, and state, so treat any single figure as a starting point.
Not every claim runs smoothly. Drivers describe adjusters pushing back on parts they consider outside normal wear, and a few describe shops that treated an approval as a ceiling rather than a budget. Coverage quality tracks the age of your car and the complexity of its components far more than the size of your monthly payment.
Who Gets the Most Value
This coverage suits owners who keep cars past the factory warranty and drive models with expensive electronics, adaptive suspension, or complex turbo systems. Lease for three years and trade in, and the math rarely works. Owners debating the value of auto repair insurance usually split along those lines rather than along brand loyalty, which says more about driving habits than marketing.
Coverage Gaps and Exclusions
Every policy has edges. MBI usually must be added while the car is still young, often within fifteen months of purchase and under fifteen thousand miles, and it excludes routine maintenance, brake pads, tires, and cosmetic damage. Modifications rarely kill a claim; one owner with aftermarket parts had suspension and headlight work approved without argument, which genuinely surprised him.
Why Geico Repair Claims Get Denied
Authorization Process Problems
An authorization snag is not the same thing as a denial. Some independent mechanics simply refuse to work through an insurer’s approval portal, which stalls a repair before any adjuster ever inspects the car. Geico’s estimating standards then apply, and the shop either accepts the approved figure or the job moves elsewhere. Understanding that distinction early saves days of pointless arguing.
Poor Workmanship and Cheap Materials
Workmanship problems do occur inside the network. Owners have described recommended shops using cheap materials or rushed labor, then getting shuffled between adjusters before Geico finally reassigned the repair as a warranty job at a different network location. You can refuse delivery when the finish is wrong, and putting that refusal in writing protects your position far better than a frustrated phone call.
The frustrating part is rarely the first repair; it is the comeback nobody wants to own. A shop outside Geico’s network leaves you chasing a private warranty, while a network shop gives the insurer a reason to correct its own mistake. Ask who pays for a redo before you approve anything, because that answer protects your paint.
Mistakes That Cost You Money
Skipping photos before drop-off, accepting a verbal estimate, and letting rental days quietly expire are the three most expensive mistakes in this process. Each one weakens your leverage because the repair record stays thin and Geico only owes a reasonable amount. Document the car, insist on the estimate in writing, and confirm exactly who backs the workmanship.
| Risk | Why it happens | Practical fix |
|---|---|---|
| Rental overrun | Long repairs at out-of-network shops | Get the timeline in writing before drop-off |
| Workmanship failure | Rushed prep or cheap materials | Refuse delivery in writing, request warranty reassignment |
| Supplement dispute | Hidden damage found mid-repair | Photograph everything and keep the estimate written |
| Authorization delay | Shop avoids the insurer portal | Ask for reassignment to another network location |
| Parts disagreement | Recycled or aftermarket parts specified | Check your state’s consent rules for crash parts |
How to File a Geico Repair Claim
Before You Hand Over the Keys
Photograph every panel and the odometer before the car leaves your sight, then request the estimate in writing with part types spelled out. Ask directly whether the shop sits inside Geico’s network and who warranties the paint and welds. Ten minutes of documentation at drop-off prevents most supplement disputes later, because the record already shows what the car looked like on day one.
Talking to Adjusters and Shops
Keep one thread of communication with your adjuster and quote the claim number in every message. If a shop refuses Geico’s approval process, ask to be reassigned to another network location, and repeat that request calmly. Historically, adjusters were graded partly on network scheduling, so a specific, polite ask often travels further than a long complaint.
After the Repair Is Done
Inspect the car in daylight before signing anything, and test every function the repair touched. Look for mismatched paint, uneven panel gaps, and warning lights that were not there before. If something feels wrong, write it on the delivery paperwork immediately; that one line later converts a comeback into warranty work instead of a fresh, chargeable job.
Nothing here requires legal knowledge, only patience and a paper trail. Decide your shop strategy before damage happens, keep deductible expectations realistic, and treat every estimate as a negotiation rather than a verdict. Owners who document early and ask precise questions consistently report smoother outcomes than those who simply accept the first recommendation they hear.
Questions Owners Ask About Geico Auto Repair Insurance
Does Geico auto repair insurance let me pick any shop?
Yes, in nearly every state you can choose your own shop. The catch is warranty coverage: Geico guarantees workmanship at its network locations for as long as you own the vehicle, while an outside shop answers only to its own warranty. If a comeback happens two years later, that difference decides whether you pay or someone else does.
Is Geico Mechanical Breakdown Insurance worth it for older cars?
Usually not, because MBI has to be added while a car is still new, generally within fifteen months of purchase and under fifteen thousand miles. Once a vehicle ages out, third-party contracts become the only route, and their value depends heavily on exclusions. Owners with expensive electronics and adaptive suspensions tend to get the most back.
Why would Geico deny or delay a repair claim?
Most delays come from authorization and documentation rather than outright refusals. A shop that will not use the insurer’s portal, an estimate above what adjusters consider reasonable, or pre-existing damage all slow things down. Denials usually hinge on whether the damage traces to a covered event, so photos and a written estimate carry real weight.
Can Geico insist on aftermarket or recycled parts?
It can in many cases, and several states require disclosure or your consent before non-OEM crash parts go on. Modern driver-assistance sensors complicate this further, because bumper and windshield work often needs recalibration that some aftermarket parts cannot support. Ask for the part list in writing and compare it against your state’s consumer rules.
How fast does Geico pay a repair claim?
Straightforward network repairs often clear within a few business days once the shop submits the estimate, while supplements for hidden damage add time. Rental allowances usually run out before long repairs finish, which is why timeline promises matter. Ask for the payment schedule in writing rather than relying on a phone summary.
What should I do if I am unhappy with the finished repair?
Refuse delivery before you sign, note the problem on the paperwork, and request a warranty reassignment to a different network shop. Insurers respond to documented defects far faster than to verbal complaints. If the shop sits outside the network, your leverage shifts to its own warranty and any state consumer protection process.
Further reading worth your time: state insurance department consumer guides on crash parts disclosure, NAIC model language on aftermarket parts, and I-CAR repair standards covering ADAS calibration. None of them sell insurance, which is exactly why they are useful when you are deciding what to accept.